
Tags

Ethan Mills
Associate Manager, EMEA Sales
October 19, 2026
3 min read
Investment managers already collect enormous amounts of portfolio data for regulatory and operational purposes. But what if some of that data could be used to identify opportunities to recover money that would otherwise be left unclaimed?
That was one of the key ideas explored during a recent SS&C webinar, Beyond Compliance: Unlock Operational Alpha with Regulatory Excellence & Securities Recovery, on unlocking operational alpha. The discussion, led by Richard Clark, SS&C GlobeOp Regulatory Solutions, Managing Director, & Ethan Mills, SS&C GlobeOp, International Hedge Fund & Class Action Recovery Services, Business Development, and moderated by Giles Smart, SS&C GlobeOp Regulatory Solutions, Managing Director, examined the connection between regulatory reporting and securities litigation recoveries. Specifically, how Form 13F data can provide a starting point for identifying potential recovery opportunities.
A Significant Opportunity can be Overlooked
Securities class actions generate substantial settlement funds for eligible investors. Hundreds of new class action cases are filed each year, with billions of dollars in settlement funds available for distribution.
Yet many investment managers do not have a systematic process for identifying and claiming their eligible recoveries. A 2026 HedgeWeek survey of 100 hedge funds showed four out of five respondents did not have a proactive process for capturing class action recoveries.
There are several potential barriers, including limited awareness, resource constraints, barriers limiting maximum recovery and the lack of specialist expertise. Some managers may also assume that pursuing securities litigation requires getting involved in the underlying legal proceedings. In practice, the recovery process is different.
The Opportunity Starts with Data
For managers subject to Form 13F reporting, quarterly holdings data can provide an initial screening mechanism for the SS&C Battea team. That information can be compared against securities class action cases to determine whether a manager's holdings potentially overlap with an eligible class or settlement period. The process can therefore look something like this:
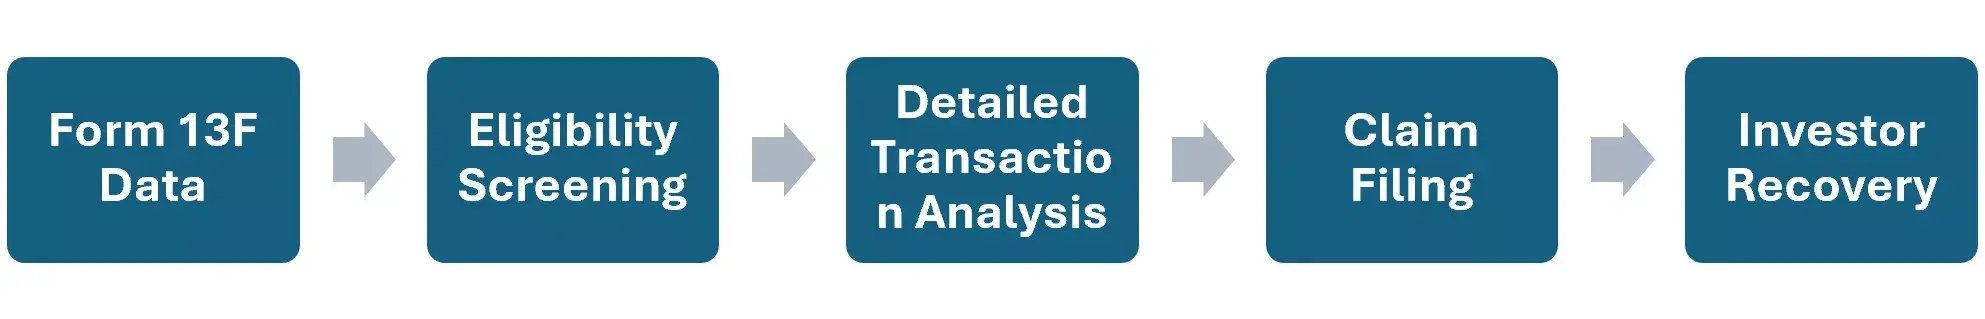
The crucial point is that the original dataset already exists. The challenge is connecting it to a process with the specialist expertise needed to interpret securities litigation activity and identify relevant recovery opportunities.
Screening is Only the Beginning
Once a potential case has been identified, more detailed information may be required. Transaction and holdings data can be used to establish eligibility and calculate the information needed for a claim. The process also requires an understanding of each settlement's rules, eligibility periods, documentation requirements and filing deadlines.
This is becoming even more complex outside the US.
International securities litigation can operate differently, including through opt-in structures where eligible investors must actively participate. Identifying opportunities can therefore require monitoring across jurisdictions as well as relationships with law firms, litigation funders, and other market participants.
The data may be sitting inside the investment manager. The expertise required to interpret that data against thousands of potential cases is a separate challenge.
Build It Internally or Outsource It?
Managers looking to establish a recovery process generally have a choice between building internal capabilities and working with a specialist provider. An internal process may require operations or legal personnel to take on another recurring responsibility. That creates resource and expertise considerations.
An external process can centralize the monitoring, eligibility analysis and filing activity, while leaving the manager with an oversight and review role.
A common misconception is that participating in a securities class action recovery means that an investment manager is becoming a litigant or initiating a legal case. In many circumstances, the underlying litigation has already progressed through the courts, and a settlement has been established. The recovery process is about determining eligibility and submitting the appropriate claim.
A New Way to Think About Operational Alpha
The broader lesson goes beyond securities litigation. Investment managers often look for operational improvements by asking where they can automate an existing process or reduce its cost. There is another question worth asking:
What additional value can be created from data and processes that already exist?
Regulatory reporting provides a particularly clear example. A dataset created to satisfy a mandatory reporting requirement can also help identify potential settlement recoveries. The same information can therefore support both compliance and a potential source of additional value.
That is operational alpha in a practical sense: finding opportunities within the infrastructure that already exists, rather than necessarily building something entirely new.
Watch the on-demand webinar to learn more.